Thursday, 23 January 2025

Income Tax Rates: Financial Year 2024-25 for Salaried and Individuals

The Income Tax Slabs and Rates were amended during previous financial years by introducing the new tax regime in 2022-2023 and making subsequent amendments.

So, from the financial year 2024-25 (AY 2025-26), our Indian government has made the new tax regime the default regime.

But, the taxpayers can opt out of the new tax regime and choose to be taxed under the old regime.

  1. For non-business taxpayers, the option can be exercised yearly while filing the ITR returns. So, they can switch back to the old regime or return to the new regime each year as per their likes and whims.
  2. However, people with income from other sources, such as business, investments, or professional services, have this option only once in their lifetime: to switch to the old regime or switch back to the new regime.

To utilize this one-time option, they must furnish Form 10-EA on or before the due date of filing the return.


Old Tax Regime vs New Tax Regime

If you choose the old tax regime, you can claim deductions under various options of Chapter VI A of the Income Tax Act, such as HRA, LIC premiums, contributions to EPF and pension schemes, interest received from banks, health insurance premiums, medical treatment, interest paid on home loans, etc.

But the above deductions are not allowed if you opt for the new regime. In such cases, only the interest paid on house loans, contributions to the Central Government Pension Scheme (14%), and contributions to the Agnipath Scheme are allowed.

In either case, you will be paying more or less the same amount of tax (as both calculations are designed to squeeze as much tax as possible, so there won't be much variation).

Now, let us have a look at the Income Tax slabs and Rates for Salaried Individuals.

Income Tax Slabs and Rates

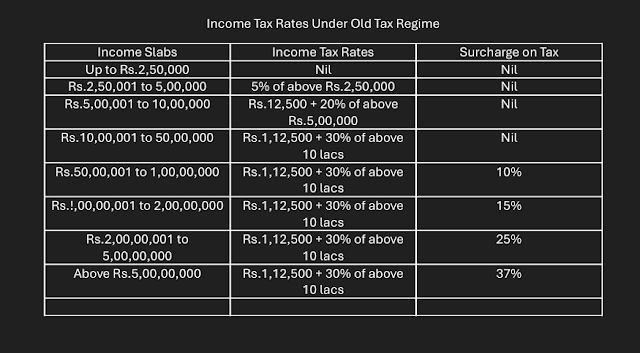
I will provide the income tax rates for the new regime first, and then the rates under the old regime.

Please note that these slabs and corresponding rates apply to individuals below the age of 60 and not to others.

Slabs & Rates Under New Tax Regime:


Old Tax Regime


Note:-
Deductions under specific sections are allowed for those opting to be taxed under the Old Tax Regime as per the prevailing old practices, prior to the introduction of the New Regime. These allowances shall be discussed in my upcoming articles.


Saturday, 31 December 2022

Concepts of Total Revenue, Average Revenue, and Marginal Revenue

Let us study the nomenclature of revenue in three distinct concepts of total revenue, average revenue, and marginal revenue.


Total Revenue

Total revenue refers to the total receipts or income made in business during a period. It is the whole/gross income from the sale of goods and services and does not include other receipts. But normally, it is treated as the product of quantity sold multiplied by the price per unit sold.

So, Total Revenue = Total quantity multiplied by price per unit.
It can be represented as TR = Q*P, where TR is total revenue, Q is quantity sold, and P is the price per unit.

Average Revenue

Average revenue is the revenue or cost per unit of production or sales.
 
Generally, businessmen arrive at the average revenue by calculating the per-unit average of total expenses incurred in producing their output, which includes the value of their own minimum profit and other expenses like remuneration for staff and management. 

So they have to recover this average price through sales. The price is fixed by them accordingly. So, in most cases, the average revenue will be equal to the average cost of that product. Only then can they realize the full production cost.

Average revenue is calculated by dividing the total revenue by the number of units sold.

Average revenue = Total revenue / total quantity sold
AR = TR/ Q, where TR is total revenue and Q is quantity sold.

But we have already noticed that TR is Q*P as per our Total Revenue concept.

So, if we substitute TR with Q*P, then AR = Q*P / Q = P.
 
So, AR is the same as P. This is applicable in most of the cases.

Marginal Revenue

Marginal revenue is the amount of revenue received by selling one more unit of the product. It is the change in revenue divided by the change in quantity sold.

Under normal circumstances, if cost or price remains constant, then Marginal revenue should equal Average revenue. But, in most cases, it is not so.

This is because if there is plenty of supply, the prices will fall naturally. On the other hand, if there is a shortage of goods, people tend to pay more for them rather than forgo them. 

So, Marginal Revenue cannot be equal to Average Revenue.

This is why the need for the concept of Marginal revenue arose.

Marginal Revenue is calculated by subtracting the additional revenue earned from the total revenue.

Marginal revenue = P*(Q+1) - P*Q, where P is the price or cost per unit, and Q is the quantity.

So, MR = the revenue received by selling (Q+1) units minus the revenue received by selling Q units.

For example, if a vendor sells each pair of slippers at Rs.100 per unit and suppose he sold 20 units on one day and 21 units the next day. 

If you want to know your marginal revenue for the next day, on the second day he sold one extra unit. First day TR was 100*20 = 2000, and second day's TR was 100*21 = 2100. His MR for the second day is Rs.100. 

 But we are not concerned with the additional revenue if the price remains the same.

Marginal revenue makes sense only when prices keep escalating.

Suppose he sold 20 units for 100/per unit on the first day. 
The next day, he was able to sell 21 units and earned only Rs.2080 as he had to sell the extra unit at a lower price. 

Therefore, MR will be only Rs.80, because he earned an extra amount of only 80 (2080- 2000 = 80).

Key Facts about Average Revenue and Marginal Revenue

  • Calculation of Average Revenue is done to determine the price of a product. This helps in managing fixed costs and in determining production levels.
  • Marginal Revenue calculations help in determining sales volumes so that additional units of sale can be withheld after reaching a certain point by withdrawing the stocks from the market or by controlling production quantities.
  • Average revenue (AR) or Marginal revenue (MR) can increase or decrease depending on circumstances.
  • If fewer units are produced, AR will increase because many costs are fixed regardless of quantity, so the price per unit will be higher. Conversely, if more units are produced, AR per unit will be lower.
  • Similarly, MR changes with quantity at certain levels. If more units are sold beyond a certain point, marginal revenue per unit will continue to decrease. If fewer units are sold than the market demands, MR may increase per unit sold.
  • Average Revenue is calculated at a particular level of sales to determine the average price realized and to compare the cost price with the sale price.
  • Marginal Revenue is calculated to study the impact of selling each additional unit. It is used to control sales volume and maintain price.
  • AR and MR will be the same as long as the seller can maintain the same sale price for any volume of sales.
  • If the seller is unable to maintain the same price at each level of sales quantity, then AR and MR will vary.

Wednesday, 16 November 2016

Elasticity of Demand- Price Elasticity and Arc Elasticity Methods

Elasticity of Demand

The term 'elasticity of demand' refers to the responsiveness of demand to changes in the price of a given commodity, assuming all other factors remain constant.

To be more specific, the Price Elasticity, or "Elasticity of Demand," is a measure used to determine the percentage change in the quantity demanded of a good or service in response to a one percent change in the price of that good or service.

We are all aware that whenever the price of a commodity increases, we tend to curtail our demand for that commodity. So, the tool of the elasticity of demand tries to measure the magnitude of those changes in demand with reference to the changes in the price of that commodity.

The Elasticity of Demand is also known as the price elasticity of demand.

These terms are expressed in abbreviated form, either as "Ed" or "PED", respectively.

The elasticity of demand is mostly negative in almost all cases except in cases of "status goods" (Veblen goods) or "goods that have no substitutes" (Giffen goods).

Veblen goods are luxurious items that are the status symbols of extremely wealthy people.

Giffen goods are basic, non-luxury goods that have no substitutes. They are necessary for survival when the prices of other staple items rise. Bread, potatoes, and rice are essential for a common man to survive. So, he has to buy them when no food is available, even at higher prices.

How to Measure Elasticity of Demand?


The Elasticity of Demand is measured with the help of formulas just like Elasticity of Supply.

The general equation for Price Elasticity of Demand is expressed as follows:

Price Elasticity of Demand = Percentage change in quantity demanded divided by Percentage change in Price

So, if the original quantity is Q and the price is P, then Ed = (dQ/Q)/ (dP/P)

In the above equation, Ed denotes the elasticity of demand (price elasticity).

DQ refers to the change in quantity, and Q refers to the original quantity demanded.
DP points to the change in price, and P to the original price.

You can express the above equation as (Qd1/Qd) / (P1/P), where Qd1 denotes the changed quantity, and Qd denotes the original quantity. P1 is the new price, and P is the original price.

But we know that when prices increase, demand for those items decreases, and demand increases whenever prices fall. 

So, there is always an inverse relationship in the equation, except in the cases mentioned above. Hence, the equation always gives a negative value.

Two more precise, result-yielding formulas are being used by economists nowadays to measure the elasticity of demand. 

These formulas are as follows:

1) The Arc Elasticity of Demand formula
This method is used when there is no exact equation for demand available or when we are not accustomed to taking derivatives.

2) The Point-Price (or Price-Point) Elasticity of Demand formula
This method is used when we have the exact equation available, or when we are capable of calculating the derivatives of equations.

Now, let us study these two methods of calculation, one by one:

Arc Elasticity of Demand Method

The arc elasticity method gives us the average elasticity of demand between two end points of an arc on a demand curve. So, it gives us the average elasticity of demand for that curve. 

It solves the problem faced by analysts in choosing one point as the original point and the other point as the new point and, thereby, provides great relief from the dilemma faced by economists in calculating the elasticity. 

But it may not provide accurate figures, as you are taking the average of two points on a curve.

The mathematical equation for arc elasticity of demand is as follows:

{(P1+P2)/2} / {(Qd1+Qd2)/2} x (change in quantity demanded/change in price)

So, Elasticity of Demand according to this formula = (the average of prices divided by the average of quantities demanded at each price) x (change in quantity divided by change in price)

You are taking the average of multiple prices on an arc and dividing it by the average of new quantities demanded by consumers at those changed prices. Thereafter, you are multiplying the same by the derivative of (change in quantity divided by the change in price) at any point to decide the elasticity at that point.

Suppose there are two price levels for a commodity, sugar, at Rs. 40 per kg and Rs. 50 per kg.
Let us assume that at price 40, quantity demanded is 10 kg, and at 50, quantity demanded is 8kg.

Now, according to above formula, Ed = {(40 + 50)/2 divided by (10 + 8)/2} x {(10 - 8) divided by (40 - 50)} = (90/2 divided by 18/2) X (2/10) = (45 divided by 9) X (2/10) = 5 X 0.2 = 1
So Ed = 1

1% change in original price is 40 x 1/100 = 0.40 = 40 paise.

According to this formula, for every 40 paise, the quantity is assumed to change by 1%.

Point-price Elasticity of Demand Method

The point-price method is used to determine the elasticity of demand at very small changes in prices. 

It is useful in determining the price elasticity of demand at a specific point on the demand curve. 

It studies the changes in demand at price points very close to each other on a demand curve.

It also uses the same formula: the percentage change in demand divided by the percentage change in price. 

But instead of calculating each equation, we take information from the demand equation to calculate the price elasticity of demand.

Ed = percentage change in demand / percentage change in price = (Qd1/Qd) / (P1/P) = (P/Qd) x (Qd1/P1)

Now, as I mentioned above, this method is applied when we have the exact equation for the demand curve and the derivatives with respect to price.

Let us take an example:

The equation for the elasticity of demand for a demand curve Q = 5000 - 50P

So, in this equation, Qd1/P1 = 50 (per one unit of price, the change in quantity demanded is 50).

Now, suppose we have to find the point-price elasticity of demand at prices of 40 and 25.

The quantity demanded at 40 will be 5000-2000=3000. (multiplying 40 by 50)
The quantity demanded at 25 will be 5000-1250=3750. (multiplying 25 by 50)

So, Ed at 40 is -50 (40/3000) = -2000/3000= -2/3= -0.666
Ed at 25 is -50 (25/3750) = -1250/3750= -1/3= -0.333

Monday, 3 October 2016

Saving, Insurance and All About their Business

Saving and Insurance are two major economic activities, just like capital formation and other activities. These two are becoming a part of the daily lives of our modern economy. 

People have become somewhat aware of the insecurity of their lives and have begun to realize the need to secure their future by saving a little from their current consumption habits and by adopting insurance policies.

Saving


Need for Saving
If people go on consuming and spending all their income, and producers go on producing and thereby utilising all the resources of the economy, a day will come when there will be nothing more left to produce or to consume. So, people should curtail their consumption and spending habits and save some money and resources for future and emergency needs.

Meaning and Definition of Saving
"Saving is that portion of income or the excess value of the resources that has been left unused or unspent in a given period of time."

Saving is different from 'Savings'. 

Saving is an economic activity, whereas 'savings' is an accounting term. 

  • Savings is only a part of the total act of Saving.

In Keynesian economics, "Saving" has been defined as the excess of the amount or value left out of the available resources after consumption. 

So, saving is an economic term that points to the "total pool of savings" accumulated during a period of study.

  • The total saving of an economy can be considered as the total income or value of the resources less the total expenditure or value of the resources consumed by that economy in a given period.

Suppose a person 'X' received an income of Rs.6,00,000 during a year and spent a total of Rs.5,00,000 during that period; then, the balance of Rs.1,00,000 is his savings during that year.

So, when we add all the amounts of similar savings created by each and every member of that economy, it is the total Saving of that economy.

  • Saving not only constitutes the money saved but also includes the value of all the resources saved.

How to Save?

You can start with a very simple method. Try to be conscious of saving at every step. You can save even a few coins or rupees from your purchases and collect that money in a safe place. 

You will experience the wonderful results of that habit. After a month, you may find that you have saved as much as Rs.500 or even Rs.5,000 depending upon your saving habits and income. Now, you can deposit the money in a Bank. Maintain this practice continuously and make it a habit. This is the simplest thing to do if you are conscious of it.

Besides the above, you can save lump sums at periodic intervals, whenever you receive some extra income such as Overtime payments or Bonus, etc. 

Invest the saved amount in FD's or other Investment schemes.

Similarly, Producers and Manufacturers can also save much of their resources utilised by following some simple economic methods of production. 

  • Experiment with different ingredient ratios in production to minimize input quantities and costs.
  • Implement techniques such as identifying waste during material handling and/or leaks, and managing labor efficiency, etc.
The above are some ideas for saving resources.

Benefits of Saving to the Economy

Whenever people save some amount of their income, they generally deposit it in Banks or invest in some investments like FDs, stocks, or Debentures, etc.

Bank deposits lead to the availability of ample funds with Banks. 

As they are not going to be immediately withdrawn by all of them at the same time, Banks are naturally left with idle funds for a certain period. 

So, they can utilise these funds by lending to needy customers who are willing to take loans to meet their urgent requirements and then return the money along with some interest at a later time, either in instalments or in one lump sum.

In that way, Banks earn income from idle funds, and thereby, they can pay some "interest income" to their depositors in return for keeping funds in the bank.

  • So, you can see that the money saved by people not only creates extra income for themselves as well as for banks, in the form of interest, but it also helps other people meet their urgent and unforeseen expenses because of this saving habit of people.

Besides this, the money saved and deposited in banks or invested in shares, debentures, or government bonds helps businesses and industries further augment their production and add to the growth of the economy. 

  • The money saved results in increased production and in increased capital formation. 

  • The money invested in Government Bonds helps governments to utilise the money for public welfare programmes like constructing roads and dams, irrigation canals, parks, schools, and for many other purposes like providing subsidised schemes, midday meals to school children, etc., which all result in the welfare of the public and the growth of the economy as a whole.

Insurance

Importance of Insurance
Life is always uncertain. It is more so in this present-day world. People often get sick due to polluted water, air, and atmosphere that are causing or spreading so many viral infections. 

Impoverished roads and surging vehicular traffic are also a cause for concern, as they can result in accidents. Even the habits of people are deteriorating their health and resulting in premature deaths.
 
Natural calamities, accidents, thefts, and burglaries all cause huge loss to property. 

So, everything needs to be protected with a suitable insurance cover. Insurance provides great relief to people as it reimburses them an ample portion of the losses suffered by them.

Meaning and Definition of Insurance

Insurance is a helpful tool available for the security of the people. It is a kind of assurance from an undertaker to provide compensation for a certain loss suffered by the victim, like death, accident, fire, etc., in consideration of a nominal premium paid by him at the time of purchasing that assurance.

Insurance can be defined as "an arrangement or contract whereby a party or company facilitates its customers by providing financial compensation for the loss or damage incurred by them". 

It is generally represented by a policy that guarantees to indemnify against loss in consideration of a one-time or periodic premium paid by the victim.

Insurance Business and Income to Insurance Companies

An insurer bears the risk and assumes the responsibility of reimbursing the insured person a certain percentage or amount of loss, in the event of loss or damage as covered in the agreement.

As a return for their services, they collect monthly or periodic insurance premiums from their customers as their charges. 

Since people are always insecure about their lives, properties, and health, they look to these insurance coverages as their refuge. 

Many people opt to purchase these insurance policies. As a result, the insurance business generates a large pool of funds for the insurance company, from which reimbursements are made to customers who incur losses.

But the actual losses incurred by customers may not occur during the same period. Furthermore, not all customers suffer losses in reality. Only a portion of them will claim reimbursements at any given period. 

So, the companies can invest most of the money collected in profit-yielding investments or in real estate businesses and thus earn good profits from their insurance business.

The premiums are calculated to include all expenses of the company so that they can withstand any claims of huge losses and still sustain their business. 

By managing the risk in an intelligent and smart way and by evaluating the weak points minutely in all respects, the insurance companies can make ample profits and minimise their incumbent reimbursement occasions.

Different Types of Insurance Policies

There are many types of insurance policies to cover different types of losses.

a) Life Insurance
The life of a person is insured under this cover. 

Insurance companies examine the individual's health history and determine the amount to be reimbursed under the policy. Normally, younger people can opt for higher coverage with lower premiums, whereas older people are covered only for lower amounts, and even then at higher monthly premiums. This is because older people's life expectancy cannot be predicted as accurately, and it is riskier for insurance companies to underwrite their policies.

b) Health Insurance 
Health insurance policies cover hospitalization and medical expenses. 

These policies also require periodic premium payments to cover these expenses. The policies are issued annually.

The health of the person concerned is thoroughly examined before determining the amount to be reimbursed. You can renew policies annually. Most MNCs provide their employees with this health insurance coverage nowadays. Medical expenses are reimbursed by insurance companies after verifying the bills and expenses. Some expenses are not reimbursed during the process because they are deemed unnecessary by the insurers.

c) Personal Accident Insurance
Personal accident policies cover injury or death resulting from accidents. They cover only accident-related cases. 

The sum assured is generally limited to 5 or 6 years of the person's job earnings. It does not take into account other income. If the insured dies or suffers a serious, irrecoverable loss of limbs, the insurer will reimburse the full sum assured. Otherwise, only a portion of the sum assured is paid based on its norms. The insured needs to pay a premium to activate the policy.

d) Auto Insurance
Auto insurance covers the damages incurred by vehicles due to accidents or other calamities. The insurance amount is calculated based on the value of the vehicle according to its ageing factor also. A new vehicle can be insured for its whole cost with a higher premium payment. Old vehicles are insured for their residual value only with lower premium payments.

5) Other Insurance Policies
There are many other insurance options available for almost all kinds of damages or losses suffered by people. 

Some of them are Fire Insurance, Theft or Burglary Insurance, Marine Insurance (for losses suffered during shipwrecks, etc.), Fidelity Insurance (losses due to dishonesty, etc. during employment), Travel Insurance, Credit Insurance (loss due to bad debts), Crop Insurance (for farmers due to natural calamities), Workmen Compensation Insurance (loss incurred during employment due to negligence of employer resulting in accidents).

Wednesday, 28 September 2016

Meaning and Definition of Bank | Functions of Banks

A Bank is an organization that is licensed by the government or law to receive and safeguard deposits from the public, sanction loans, and to act as an intermediary in their financial transactions.

Banking institutions have been in operation since ancient history, when funds were pooled and loans were sanctioned to farmers and small traders for the overall development of economic conditions in their respective areas or kingdoms.

The modern banking system had its roots in the aftermath of the Renaissance in Europe. 

Thereafter, gradually, the modern banking concepts and practices developed from the 18th century onwards, resulting in the present banking system and practices.

Definition of Bank

A Bank can be defined as follows:

"An establishment authorized or licensed by a government to accept/ receive deposits, pay interest on those deposits, issue loans, act as an intermediary in all financial transactions, and provide other related financial services to its customers."

Functions of Banks

From the above-cited definition, it is evident that Banks perform all types of financial transactions like receiving deposits from their customers, maintaining their accounts, safeguarding those deposits and allow withdrawals or payments from those deposits, pay interest on those deposits, collection or payment of cheques and bills on their behalf, provide debit or credit cards based on those accounts to enable easy transactions of funds from any corner of the world, etc.

Now, these functions of banks can be grouped into two distinct sub-groups. 

They are primary functions and secondary functions. Let us discuss both these types of functions in detail.


Primary Functions of Banks


The primary functions are also known as the main banking functions. Banks (mainly commercial banks) perform many banking functions, such as accepting deposits and lending loans and advances in various forms.

A) Accepting Deposits


i) Current Account Deposits:
These accounts are mainly suitable for business people who need to make daily transactions, including depositing cash or checks and withdrawing cash or making bill payments by check or draft. 

These accounts are also known as Demand Accounts, as banks should pay these amounts immediately on demand by the depositors, without any limits or restrictions. 

No interest is paid on these accounts. Some service charges are debited to the account depending on the nature and volume of transactions.

ii) Savings Deposits:
Savings deposits are aimed at creating a habit of savings among people. 

These deposits provide an incentive of interest to the customers (it used to be 4% to 5%, but nowadays it is only 2 or 3 per cent). The interest gets credited to their accounts quarterly. There is a ceiling on withdrawals, presently 3 times per month. Any extra withdrawal is charged with some fees.

iii) Fixed Deposits or Term Deposits:
Fixed Deposits are also known as Term Deposits because they are deposited for a particular period or term. These deposits carry higher interest rates depending upon the period of deposit and as per the prevailing interest rates of those banks.

Deposits made for shorter periods will be paid lower interest rates, and longer periods will be paid higher rates. The current applicable rates are approximately 4% to 8%, varying according to the period.

The minimum period of deposit is 7 days and the maximum period is 10 years.
If you withdraw money before the maturity period, penalty charges are imposed, and the amount is deducted from your maturity balance, calculated as of the day of withdrawal.

iv) Recurring Term Deposits:
These are known as Recurring Deposits and are generally treated as Term Deposits and carry the same interest rates and rules as governed under Fixed Deposits.
The only difference between Recurring Deposits and Fixed Term Deposits is that in Recurring Deposits, you enjoy the facility of depositing monthly denominations of the deposits instead of a lump sum deposit.
These deposits are suitable for those who want to save money but can not afford a one-time deposit.

The interest provided ranges between 4% and 7%.

The minimum deposit accepted is Rs. 1,000, and thereafter, you can deposit in denominations of Rs.100 and above every month till maturity.
The tenure of deposits ranges from 12 months to 10 years. The interest is calculated monthly or quarterly according to the denominations deposited, and the amount will be paid on maturity of the entire period.

If you are unable to deposit an installment on time, you will be charged penalty charges from the due date to the next deposit date.

v) Money-Multiplier Deposits:
This is a new scheme launched in recent years, as far as I know.
It resembles the Term Deposits. But these schemes are launched to boost fund-pooling for Government schemes, etc.

They offer higher interest rates.
The minimum deposit is 1,000, and further amounts are in denominations of thousands. It is a one-time deposit for a fixed period. 

Premature closures attract penalties and charges similar to FDs and Other Deposit Schemes.


B) Lending of Loans and Advances

Banks lend various types of loans and advances to facilitate their customers. 

The main types of these loans and advances are classified into three categories.

i) Cash Credit:
Cash Credit is similar to a loan sanctioned generally to business people against their stocks, shares, bonds, and other securities. 

It is allowed upon opening a dedicated loan account, irrespective of their other accounts. A fixed amount of credit limit is sanctioned after evaluating the security provided.

Interest is charged on the amounts withdrawn, calculated by the number of days those particular balances are outstanding. 

Customers can enhance their credit limits by providing further securities.

ii) Overdraft:
Overdraft facilities are provided to existing account holders on request up to a certain fixed limit, based on their creditworthiness.

Whereas Cash Credit applies to business entities and traders, overdraft facilities can be obtained by salaried people, professionals, and even businesses also. 

It is generally provided after verification of his/their creditworthiness and repayment capacity. 

It can be availed for personal accounts and business accounts. 

Interest is charged on the overdraft amounts.

iii) Loans and Term Loans:
Term loans, or simply loans, are sanctioned by banks to customers either for a short-term or comparatively longer periods to facilitate their various needs upon providing some security or lien.

Some of these loans are as follows, to list a few.

a) Home Loans
b) Car Loan or Vehicle Loan
c) Educational Loan
d) Personal Loan (for short-term needs of customers like meeting marriage expenses, hospital, or medical expenses, etc.)

These loans and advances are credited to their account after approval, and the customers can withdraw the money according to their needs. 

Interest is calculated on the whole amount of the loan credited, and the loan amount is repayable in equal EMIs (including the interest amount), which is calculated according to the rates of interest prevailing at the time of the sanctioning of the loan.


Secondary Functions of Banks


Secondary functions of Banks are, generally, not performed by all banks. These may not be considered as essential functions of most commercial banks. So, they are known as Secondary Functions. These functions include many services provided by banks to facilitate customers and keep them around their banks.

The secondary functions of banks are classified into two types:

Agency Functions and Utility Functions.

The Banks charge a commission or bank charges for providing each one of these secondary functions.

1) Agency Functions of Banks


a) Discounting of Bills
Banks allow advances to their customers to facilitate their need for funds against bills of exchange drawn by them or of which they are the beneficiaries. 

The payments are made after deducting some charges. The bank will later collect the payment from the drawee of the bill or from the party that accepted the bill, by presenting it after the due date.

b) Transfer of Funds
Banks transfer funds of their customers from one account to another, from one branch to another, or to other banks both within the country and abroad at the request of customers in the form of demand drafts or mail transfers for which they charge some commission and/or bank charges.

c) Collection or Payment of Bills, etc.
Banks can also collect or pay your bills according to your instructions. 

This includes collection and payment of salaries, pensions, utility bills, interest amounts, insurance premiums, taxes, dividends, etc.

Banks charge fees for this service.

d) Portfolio Services
The banks can also provide the services of acting as your agent in the sale and purchase of stocks, bonds, and debentures, etc.

e) Other Agency Functions
Banks can also act as trustees, executors, and income-tax consultants for your deposits, deeds, wills, and funds.

2) General Utility Functions


The banks also offer other public services to facilitate and woo their customers, which are known as general utility functions.

a) Locker Facilities
Lockers are available to customers for safekeeping of their valuable possessions, like gold ornaments, title deeds, or documents.

Banks may charge some nominal fees for keeping them in the bank lockers.

b) Issue of Letter of Credit
Banks provide their customers with a letter of credit, certifying their creditworthiness, to facilitate their needs.

c) Issue of Traveller's cheques
Traveller cheques are also issued by banks to facilitate people on their journeys so that they need not carry huge cash balances with them while on a journey.

d) Underwriting of Securities
Banks undertake the function of underwriting or certifying the securities of their customers to facilitate the sales of those securities.

e) Purchase and Sale of Foreign Exchange
Banks are authorised to deal in foreign exchange transactions by RBI. 

So, they provide the services of handling the purchases and sales of foreign exchange transactions on behalf of their customers.

f) Collection of Statistics and Preparation of Project Reports
Banks collect statistics from markets on trade and commerce and can thereby provide the required information to their clients. 

They also prepare project reports for their clients.

g) Social Welfare Programmes
Banks may also indulge in the activities of public awareness, public welfare, and literacy programmes as a service to the nation.

Note:
Please collect the latest information regarding the services provided and/or the interest rates from your banks.

Monday, 30 May 2016

A Study of the Role of Money in Economy

By the role of money, I mean the part it plays in our modern economy.

Money is regarded as the pulse of our life. Without money, there is no life or activity in this modern economy. 

Everything is related to money here. From morning to evening, from birth to death, you need money for this or that.

Money plays an important role in our economy. It motivates and influences all our economic activities; consumption, production, supply, demand, and distribution are all influenced by the supply and power of money in any economy.


  • As a consumer, you can purchase goods and services and make payments in money, which is universally accepted. 
  • As a unit of exchange and as a measure of value, money guarantees the real value of all your goods and services.
  • Thus, money gets generated and circulated through our activities.
  • To be able to pay in money, you need to earn money. So, you will be earning money by doing some business or other, working as an employee in a company, or doing some labor. Money is earned through our occupations.
  • Money facilitates economic activity, creating businesses in the manufacturing and services sectors and thereby creating more jobs for more people across different fields. This, in turn, boosts the economy. 
  • Money further facilitates and ensures that goods and services are produced to meet the demands of consumers. Consumers can opt for better products by choosing from multiple options, as they are free to buy as and when they desire to do so. This is possible because of the storage value of money.
  • Money facilitates the easy transfer and distribution of goods and services to any corner of the world, as you can make payments through money.
  • Money plays another important role in equalizing the marginal utilities of consumers. Consumers are able to shift toward higher-utility goods by discarding lower-marginal-utility products, as they can distinguish differences in utility with the help of money as a standard of value, which sets the prices of goods in terms of money.
  • So, money facilitates rational distribution of income earned by consumers among different needs and necessities. The buyer can draw a picture of his income and expenses and match them with utmost utility levels within the given income.
  • Money, as a standard of value, makes the maintenance of accounts very easy, as everything is accounted for in terms of money. This facilitates accurate calculation of expenses and income for any business and aids in the fixation of the prices of their products.
  • Money helps governments to calculate and collect their taxes and plan their projects, estimate their revenue, and prepare Budgets accordingly, thereby enabling them to boost their economy.
  • Further, money enables a continuous flow of funds from one person to another and from one corner of the world to the other.

To sum up, money has different roles in our economy. 

It acts as the power of purchase. 
It serves as a store of value. 
It facilitates a continuous flow of economic activities.
It boosts businesses and trade internationally. 
It helps in the distribution of wealth. 
It aids in the progress of the economy as a whole.

Thursday, 28 April 2016

Money: Different Types of Money and Forms of Money

Do you realise that money is used nowadays in various types and forms?

Gold and Silver, Tokens, Coins, etc. are some of the types of money that we use in our daily transactions. Similarly, Currency notes, Credit Cards, Bitcoins, etc. are examples of Money.

So, money is classified into different types and forms according to its nature. 

Difference Between Type and Form of Money

  • "Type" of money refers to the underlying nature, status, and qualities that define its value.
  • "Form" refers to the physical material or technological mechanism used to store and use the money.


Types of Money


Money can be broadly classified into four major types. This classification describes the abstract nature of money, as opposed to its physical forms.
  1. Commodity money.
  2. Representative money.
  3. Fiat money.
  4. Fiduciary money.

Commodity Money:
Commodity money consists of commodities with intrinsic value. 
Gold and silver are examples of commodity money in our present economy. Their face value is equal to their real value. 

In earlier times, important commodities such as rice, wheat, tobacco, seashells, pearls, and valuable stones were also treated as commodity money. 

This kind of money is characterized by the scarcity of the commodity and the value attached to it by the parties to the transaction. 

But in the present-day economy, this kind of money is not significant, even though gold and silver are used as a store of value.

Representative Money: 
Representative money is that which can be exchanged for a real commodity or for money. 

For example, tokens, documents, or certificates issued to a person can be exchanged by the holder for real items, such as gold, silver, or any goods and services. 

Coins and paper currency can be treated as representative money. It represents the quantum or degree of value borne by it. 

Gold certificates and silver certificates are also examples of representative money.

Fiat Money:
Fiat money is any money declared by governments to be legal tender. 
This money by itself has no intrinsic value. It is not backed by any physical commodity, but is declared legal tender. 
For example, paper currency. You can not reject it. You are bound to accept it as money.

Fiduciary money
Fiduciary money is a form of money based on the trust and reputation of the issuer. 

The issuer of the instrument of money, whether a government, a company, or any trustee, promises to pay a certain amount of money or value as stated on the instrument, and the beneficiary places faith and trust in it. 

Most transactions in the present-day economy are conducted through these fiduciary instruments.

Forms of Money

Some of the more popular and common forms of physical/digital money are discussed here.

Coin Money
Different forms of coins are used, such as gold, silver, copper, bronze, and nickel, each representing a value printed on them.

Paper Money or Paper Currency
This form of money constitutes the currency notes printed and issued by the government or central bank, and financial documents such as bills of exchange, promissory notes, checks, bank drafts, etc.

Bank Money or Demand Deposits Money
Bank money is the money created through deposits made by the public into their bank accounts.

Demand deposits are funds deposited into banks by customers that can be withdrawn on demand without any prior notice to the bank. 

This money is characterized by the fact that the original physical money available with the banks is multiplied into larger volumes due to the facility of the minimum reserve ratio that banks must maintain against their actual deposits. 

So, the actual money available with the bank at any time will be much less than their account book balances, as they have lent it to the public and/or businesses as short-term loans. 

The total money created in this way can be known only by calculating the money in circulation with the public and then adding to it the actual money with banks and the value of checks or drafts in hand with the public and at the bank.  

Token Money
Token money is a form of money in which the tokens, such as coins or paper currency, have no intrinsic value but represent and guarantee the value stated on them, which is reimbursable.

Full-bodied Money
Full-bodied money is the form of money where its real value equals its commodity or physical value.

Gold coins and Silver coins are examples of full-bodied money or real money. They have the same physical value as their face value depicts. 

Standard Money
Standard money refers to the form of money used by different countries or economies for their accounting purpose. 

For example, the countries mentioned below use the corresponding standard units for their circulation and accounting purposes in their economies.
U.S.     Dollar ($)
U.K.     Pound (L)
India    Rupee (Rs.)
Europe  Euro  (E )
China    Yuan or Renminbi
Japan    Yen   (Y )

Legal Tender Money  
Legal tender is the form of money that is legally acceptable. 
You cannot reject any payment made with legal tender. 

Paper currency is fully legal tender, and you should accept all payments in that form. 

Coins are not fully legal tender. Only small payments can be made with coins, and you have the right to refuse payments made using large quantities of coins.
       
Electronic Currency or Digital Money
Electronic money, also known as e-money, is a form of money that is transacted through the internet or other digital channels. 

Funds are transferred, and payments or receipts are made through internet transactions using computers and mobile phones. 

Examples of e-money include bank deposits made using e-services of banks on the internet, fund transfers made online, claims against banks and agencies resulting from e-transfers or payments, and account settlements. 

PayPal, Google Wallet, Apple Pay, RuPay, Bitcoin, etc., are among the most popular forms of this kind of money.